According to MB Securities (MBS) statistics, the average transaction value across the entire market from early September to the end of last week was approximately 18,456 billion VND per session. This represents a 1,2% decrease compared to August and is 51% lower year-on-year, marking the lowest average liquidity recorded since the beginning of the year. Cumulatively over the past 9 months, total market liquidity reached 25,943 billion VND, a decline of 10,2% compared to the 2025 average and 9,8% year-on-year.
During a recent seminar, Le Chi Phuc, CEO of SGI Capital Fund Management Company, attributed the severe decline in stock market liquidity to the long-term credit cycle. He noted that after more than 10 years of maintaining credit growth rates significantly higher than GDP growth, the economy has approached the peak of its credit expansion cycle.
This situation has largely exhausted the room for monetary policy easing, compelling the market to accept a new, higher interest rate level from both commercial banks and the interbank market. Elevated interest rates have directly diverted capital away from risky asset channels, causing a sharp reduction in liquidity on the HoSE.
In addition, the impact of high interest rates on capital flow is often subtle and comes with a certain delay. While short-term consumption data or business results may not yet fully reflect this, the financial pressure is directly burdening economic entities that rely heavily on borrowed capital, thereby narrowing the idle money circulating in the market.
The reduction in stock market liquidity is not an isolated phenomenon; it is significantly influenced by the real estate market. SGI Capital leadership explained that real estate and stocks are closely interconnected through overall interest rates and system liquidity, with the stock market typically reacting 6-12 months in advance.
Given the large scale of outstanding credit in the real estate sector, any negative developments in this channel will have widespread effects. When real estate liquidity and prices decline, the substantial amount of capital frozen in this sector will exert pressure on the banking system, increasing capital costs and depleting capital flows from other investment channels.
Beyond domestic pressures, stock market capital flows are also contending with international financial headwinds. Le Chi Phuc observed that interest rate hikes by the US Federal Reserve (Fed) and numerous other major central banks worldwide have created pressure on developing economies. This forces the market to prepare for a continued challenging financial environment and tight liquidity in the coming period.
The difficult global macroeconomic context also explains the trend of foreign investor capital withdrawal. Historical analysis shows that for emerging or frontier markets to attract significant active capital flow, the global economy must experience broad-based breakthrough growth, led by emerging markets, alongside a weakening US dollar.
In the absence of these conditions, Nguyen Trung Thanh, Strategy Director at SGI Capital, added that a market upgrade event would only bring a relatively modest passive capital flow. "This capital is not enough to immediately shift overall sentiment", he stated.
Amidst these risk variables, the cautious attitude of professional capital also contributes to low trading volumes. According to Thanh, when interest rates embark on a prolonged upward trend without a clear peak, short-term investment opportunities carry high risk, and profit margins are not attractive enough for professional funds to deploy large-scale capital.
Consequently, capital from large fund managers prioritizes strict risk management and patient waiting. For The Ballad Fund, Thanh shared that the fund proactively reduced its allocation to interest-rate sensitive or high beta coefficient stock groups, while maintaining a high cash level. Institutional investors choosing to hold cash and protect their portfolios, rather than chasing short-term gains, has contributed to the quiet state and low capital flow across the entire market.
 |
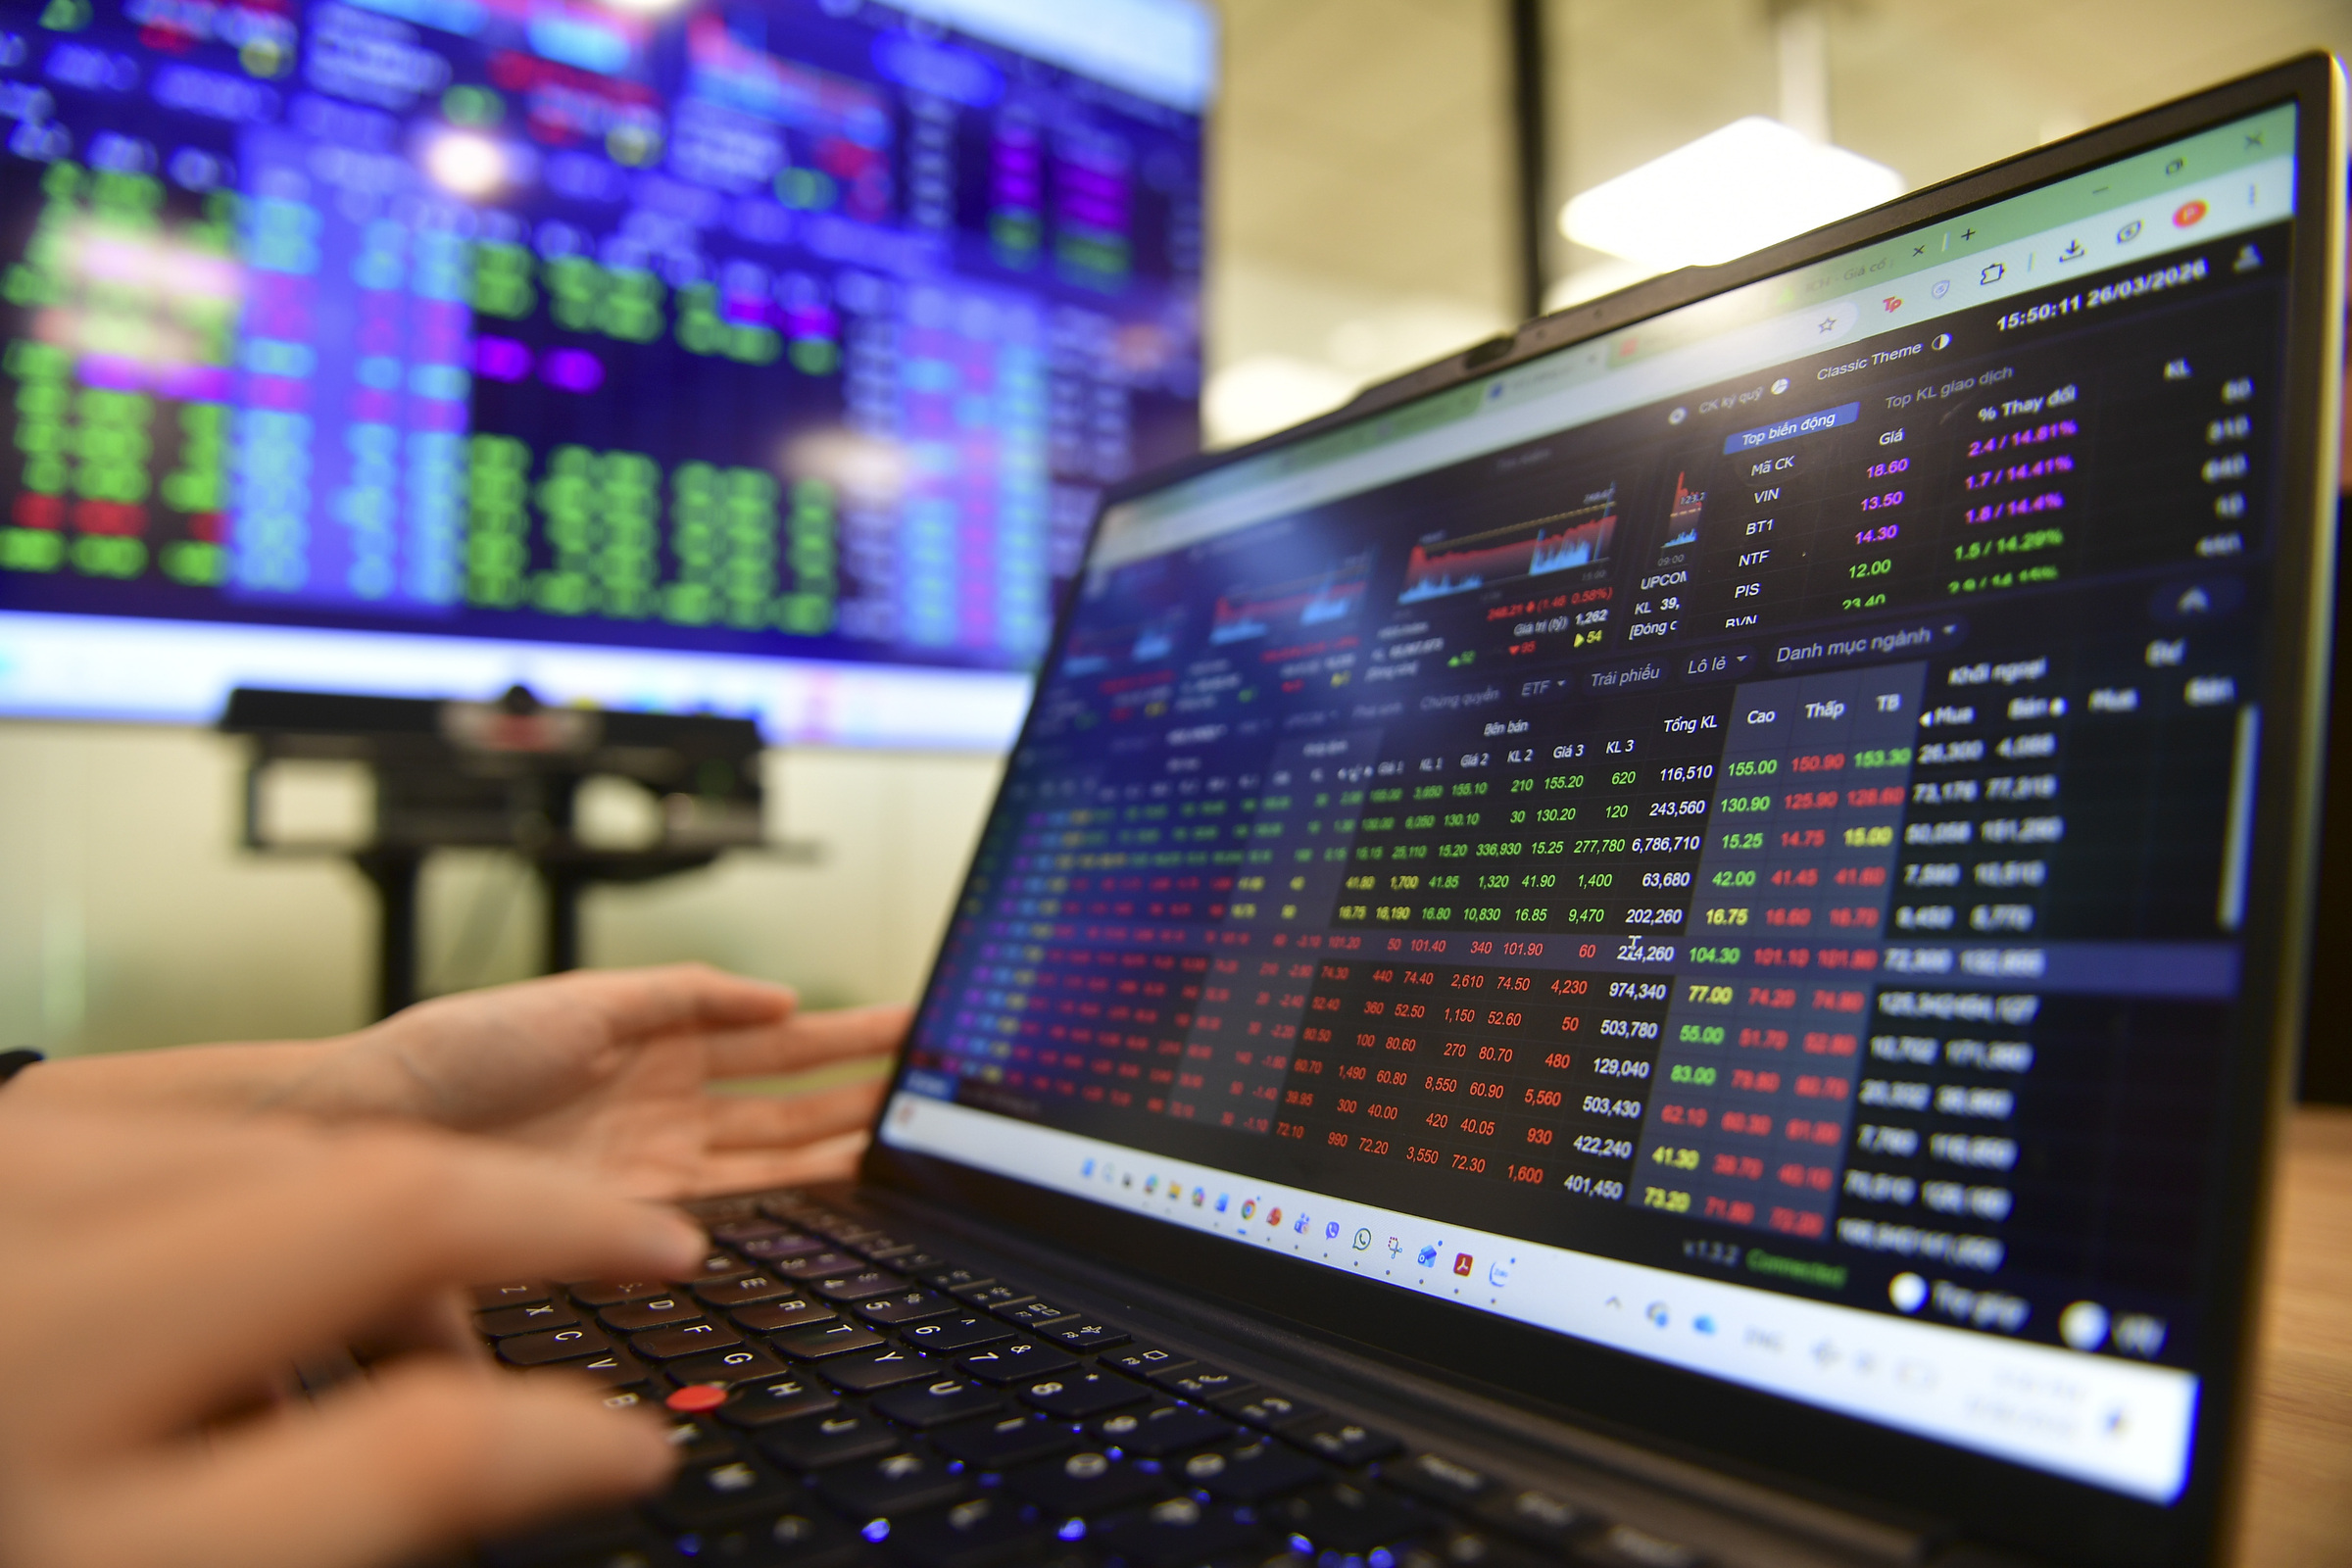
Investors trading at a securities company in TP HCM. Photo: Quynh Tran |
SSI Securities also indicates that capital flow is not yet ready for a new growth cycle. In its September strategy report, the company noted that the market is in an accumulation phase, and investors require further evidence that economic momentum is translating into a broad and sustainable earnings cycle. SSI maintains a positive medium-term outlook but suggests that developments surrounding a market upgrade event should be viewed within the context of an accumulating market, rather than assuming it marks the start of a new uptrend.
Meanwhile, Thien Viet Securities (TVS) highlighted that the issue extends beyond just liquidity size to include a lack of consensus among different capital flow groups. In August, domestic individual investors were net buyers of only 682 billion VND, a sharp decrease from nearly 16,000 billion VND in July. Domestic organizations net bought 962 billion VND, while foreign investors remained net sellers.
TVS assessed that the quality of the recovery was not truly convincing, given the declining HoSE liquidity and gains concentrated in a few stock groups. The general index surpassing resistance levels needs to be accompanied by a clear improvement in liquidity and the breadth of capital flow.
Tat Dat