At a workshop on New Dynamics for Retail and Tourism held on 25/9, Deputy Governor of the State Bank of Vietnam Pham Tien Dung announced a strong growth rate in cross-border QR payments.
According to data from the State Bank of Vietnam, the country currently has over 2,5 million payment acceptance points, with approximately 154,000 of these accepting cross-border payments.
The cross-border QR payment network is currently connected to six markets: Thailand, Laos, Cambodia, China, South Korea, and Singapore. Among these, only South Korea has enabled payment for its tourists in Vietnam.
Data from the National Payment Corporation of Vietnam (NAPAS) indicates that the volume of QR transactions by tourists from Thailand, Laos, and Cambodia surged 8 times, and the value increased 6 times compared to the same period last year.
Conversely, transactions made by Vietnamese travelers in these three markets rose 5 times in volume and 4 times in value compared to the same period in 2025.
Regarding China, NAPAS connected its cross-border QR payments with UPI late last year, followed by Alipay and Weixin Pay in April and August this year, respectively. In August alone, the number of transactions by Chinese tourists using these payment applications to scan VietQRGlobal in Vietnam increased 3 times, with the value growing 4 times compared to April.
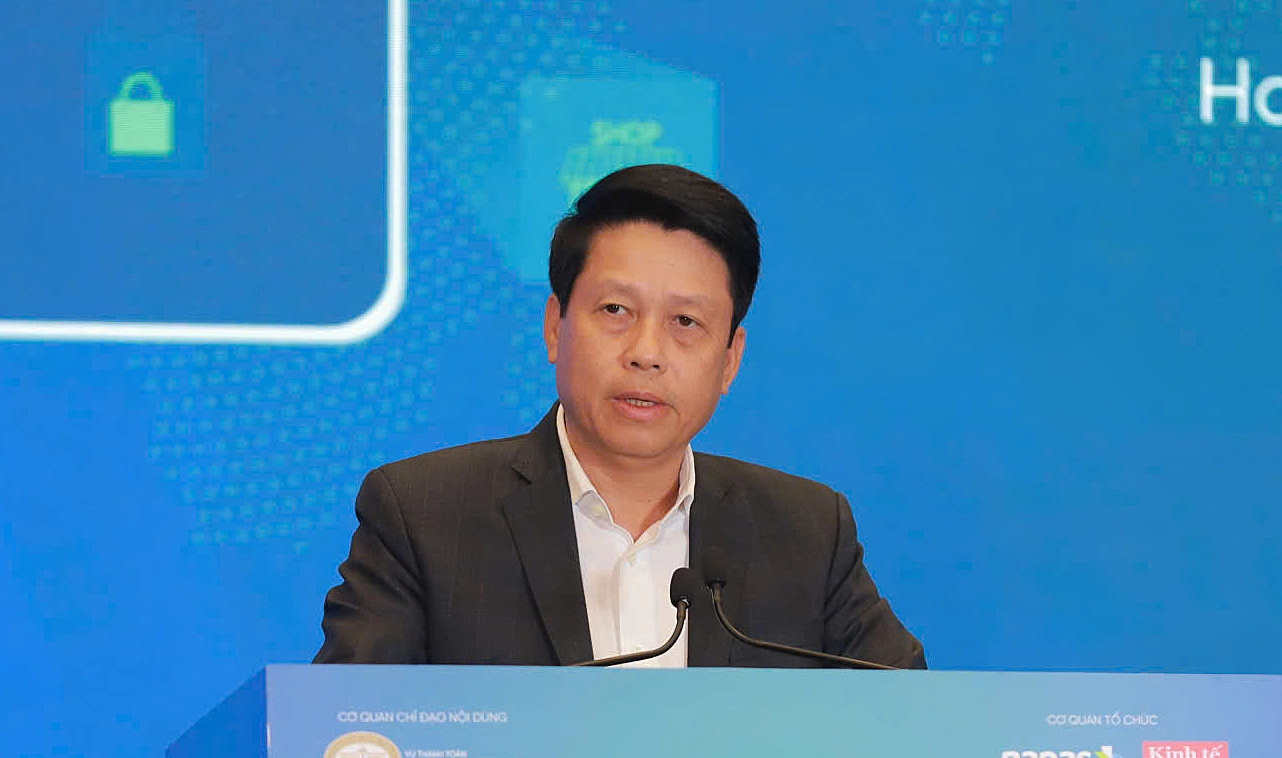 |
Deputy Governor of the State Bank of Vietnam Pham Tien Dung speaking at the workshop on 25/9. Photo: Vneconomy |
Deputy Governor Pham Tien Dung highlighted that the essence of cross-border payment extends beyond technology or a single QR code; it lies in these connections creating tangible value for the economy.
International tourists visiting Vietnam can use their familiar payment applications to pay at hotels, restaurants, shops, or individual businesses. Similarly, Vietnamese citizens traveling abroad can use their existing banking applications or e-wallets.
The banking sector leadership emphasized the need to shift focus from "connecting to achieving usability and efficiency" in the next phase. This means measuring effectiveness by the number of connected countries, the actual user base, the coverage of acceptance points, costs, and service quality.
Currently, the fee for cross-border payment acceptance is around 1,5% of the transaction value, which is lower than the 2,4-3% charged for credit cards. This difference is significant for small shops and individual businesses, a segment that can serve international customers but is sensitive to payment acceptance costs.
Expanding the network also imposes higher security requirements. When a transaction traverses multiple systems and legal frameworks, all parties must address issues related to security, fraud, anti-money laundering, data protection, and customer rights.
Nguyen Dang Hung, Deputy General Director of NAPAS, explained that utilizing a common connection hub enables banks and payment intermediaries to serve customers from various countries. NAPAS also standardizes operational procedures, technical standards, security, and supports transaction inquiries and complaint handling.
Phuong Dung